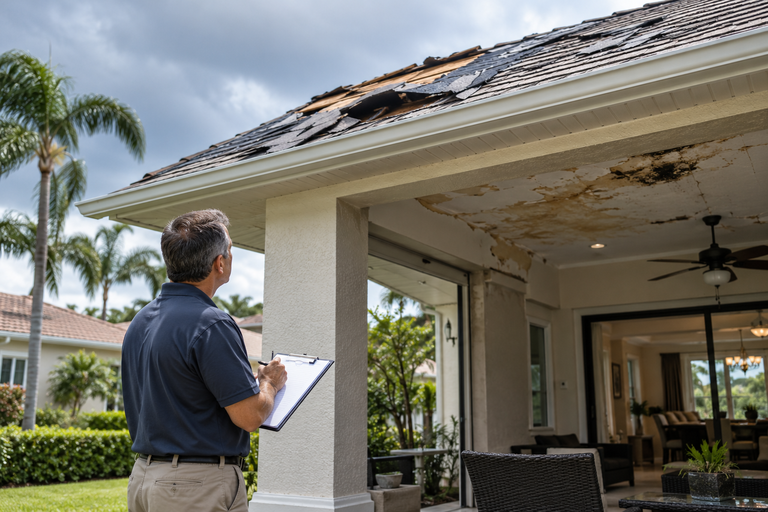
Discovering that your homeowners insurance claim has been denied or underpaid can be frustrating, especially when your home needs immediate repairs.
Insurance policies can contain detailed terms, exclusions, conditions, and limitations. Understanding why a claim was denied is an important first step.
Common Reasons for Insurance Disputes
Homeowners may experience disputes involving:
- Water damage
- Roof damage
- Storm damage
- Hurricane-related damage
- Mold
- Fire damage
- Wind damage
- Coverage exclusions
- Valuation disagreements
A denial letter should be reviewed carefully to understand the insurer's stated reason.
Request and Preserve Documentation
Keep copies of:
- Your insurance policy
- Claim correspondence
- Denial letters
- Photographs
- Videos
- Repair estimates
- Receipts
- Contractor reports
- Inspection reports
These records may become important when evaluating whether the insurer properly handled the claim.
Document the Property Damage
Photograph and video the damaged areas as soon as reasonably possible, while also taking steps to prevent additional damage when appropriate.
Keep receipts for reasonable emergency repairs and temporary expenses that may be relevant to the claim.
Do Not Ignore a Denial
A denied claim is not necessarily the end of the matter. Depending on the policy and circumstances, homeowners may have options for challenging the insurer's position.
The appropriate next step depends on the specific policy, damage, claim history, and applicable law.
What Is an Underpaid Claim?
An underpaid claim occurs when an insurer provides payment that the homeowner believes does not adequately cover covered damage.
In these situations, comparing the insurer's valuation with qualified repair estimates and supporting documentation can help identify areas of disagreement.
When Should You Speak With an Attorney?
If your claim has been denied, delayed, or underpaid, an insurance attorney can review the policy and claim documentation and explain potential legal options.
Lopez Fernandez Law focuses on homeowners insurance claims and property damage matters and represents policyholders in Florida.
Conclusion
A homeowners insurance dispute can involve complicated policy language and evidence. Preserve your documents, carefully review the insurer's position, and consider professional legal guidance when the dispute cannot be resolved.
Learn more about homeowners insurance claim representation and bad faith insurance claims.
Related Articles
Contact the Law Office of Karla Lopez-Fernandez to discuss your situation and legal options.
